Generally, no. In Texas, any refinance that lets you take cash out of your homestead must follow the state's home-equity rules (Article XVI, Section 50(a)(6) of the Texas Constitution). Those rules don't allow the VA guaranty, so a VA cash-out refinance usually isn't an option on your primary home.
If you have a VA loan, a VA IRRRL (streamline refinance) can lower your rate or payment. To tap your equity, a conventional Texas cash-out (50(a)(6)) loan lets you borrow up to 80% of your home's value.
Keep scrolling to learn why this financing option usually isn’t available on a Texas homestead and discover our recommended alternatives.
Why Is a VA Cash-Out Refinance Usually Not Available on a Texas Homestead?
The Department of Veterans Affairs (VA) offers cash-out refinance loans nationwide, allowing eligible veterans to replace their existing mortgage with a VA-backed loan and turn equity into cash.
However, while a VA cash-out refinance is available in most U.S. states, Texas homesteads are generally the exception.
Texas Homestead Law Constraints
Under Texas homestead law, veterans generally can’t receive cash-out proceeds on a VA-guaranteed refinance of their homestead.
This rule is in place to help homeowners like you preserve your equity and safeguard your homestead from creditor claims.
- 80% CLTV in a Texas Cash Out Refinance - In a Texas Section 50(a)(6) or Texas a6 loan, you can pull cash out from your primary home’s equity as long as your combined loan-to-value (CLTV) doesn’t exceed 80% of your home’s value. For example, if your existing mortgage is 50% LTV, you may refinance up to 80% and take out 30% in cash.
- 100% CLTV in a VA Cash-Out Refinance Loan - On the other hand, a VA cash-out refinance lets homeowners refinance up to 100% of their home’s value, according to federal VA rules. This clashes against the max CLTV imposed by the Texas homestead law.
- Government Guarantees Prohibited - Additionally, Texas law mandates that only your homestead property must secure the home-equity loan. Government guarantees cannot back the debt. It considers the VA’s guaranty as “additional collateral” (or loan security besides the homestead), thus prohibiting VA-backed cash-out refinances on a homestead even if you stay under the 80% LTV limit.
Key Takeaway: Texas law generally doesn’t allow VA-guaranteed cash-out refinances on a homestead because it caps home-equity loans at 80% of your property’s value and doesn’t allow additional collateral, which includes the VA guaranty.
Alternative Financing Options
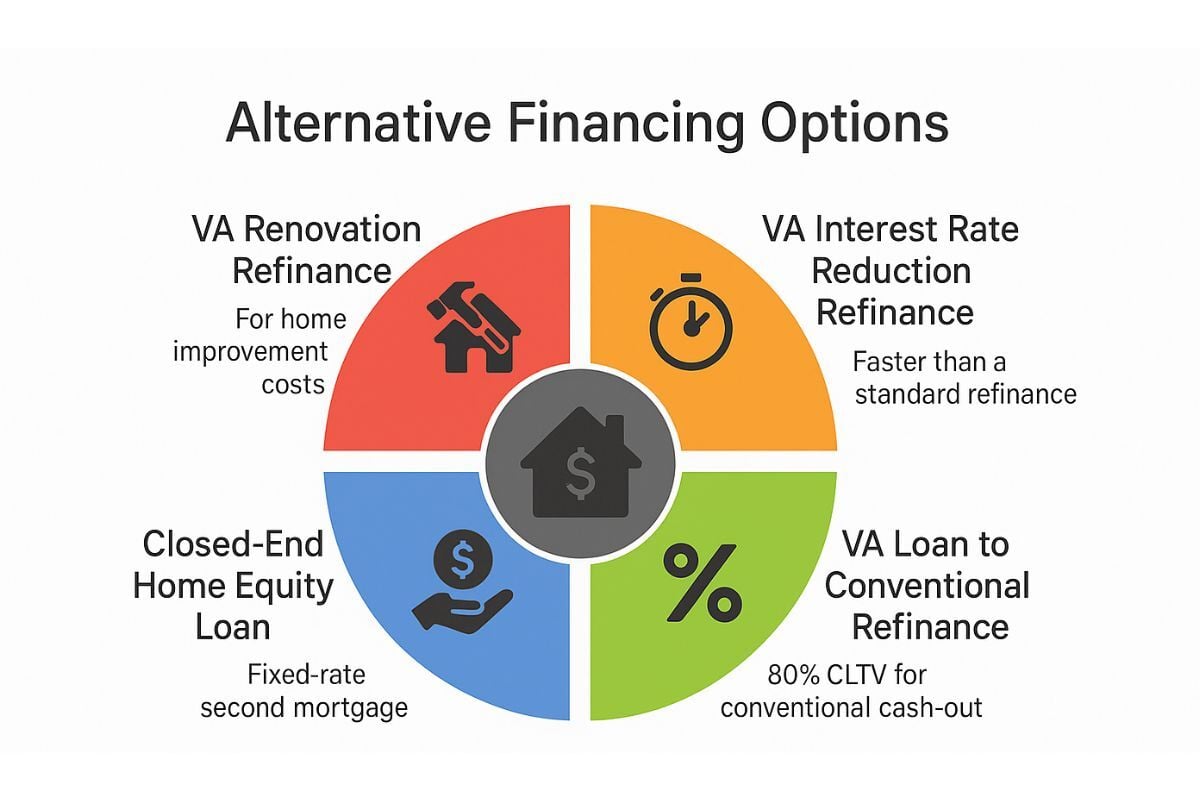
Here are viable financing options if you’re a veteran looking to refinance:
VA Renovation Refinance
A VA renovation refinance rolls your current VA loan and home improvement costs into a new VA-backed loan.
- Only for VA-approved home renovations (repair funds remain in escrow and are released after inspection of the repair)
- No down payment or private mortgage insurance (PMI)
- Financing up to 100% (some private lenders impose a 90% limit)
VA Interest Rate Reduction Refinance Loan (IRRRL)
Also called a ‘streamline’ refi, a VA IRRRL replaces your existing VA loan with a new one at a lower interest rate or lets you switch from an adjustable to a fixed rate.
- Faster than a standard refinance, with minimal paperwork
- No appraisal in most cases
- Low closing costs rolled into the loan
- No cash-out proceeds from equity
Air Force veteran David Dei Rossi and his wife bought a newly constructed property in the Bay Area without a down payment using a VA purchase loan.
With an IRRRL, they successfully reduced their interest rate from 4.25% down to 3.5%, saving around $300 on monthly payments.
VA Loan to Conventional Refinance
This lets you replace your current VA mortgage with a conventional one, pull cash out from your equity, or choose a rate-and-term (no cash out).
- 80% CLTV for conventional cash-out
- Not subject to Texas’ VA-guaranty prohibition once it’s a conventional loan
- Requires full mortgage underwriting, including property appraisal, income assessment, and credit and employment verification
Home Equity Line of Credit (HELOC)
A HELOC is a revolving second lien allowing you to tap your home equity whenever you need it.
- 80% CLTV (first lien and HELOC)
- Lower upfront costs than a closed-end home equity loan
- Variable interest means the possibility of rate increases
- Flexible borrowing
Closed-End Home Equity Loan
A closed-end home equity loan is a fixed-rate second mortgage where you receive a lump sum of financing. You make regular payments over a fixed term.
- 80% CLTV
- Predictable monthly payments
- Requires compliance with Texas home equity loan requirements, like waiting for 12 months since your last lien and having only one Section 50a6 lien at a time
Explore Your Financing Options
While Texas homestead laws generally rule out a VA cash-out refinance on your primary home, you still have different ways to access your home equity.
Choose a trustworthy lender who fully understands the intricacies of Texas homestead protections and federal loan guidelines.
At Texas United Mortgage, our seasoned loan officers specializing in cash out refinances will help you explore the best financing options for your unique financial needs.
Contact us now for a personalized consultation!
Next, learn about VA construction loans for veterans who want to buy a land and build their dream home in Texas.



Comments