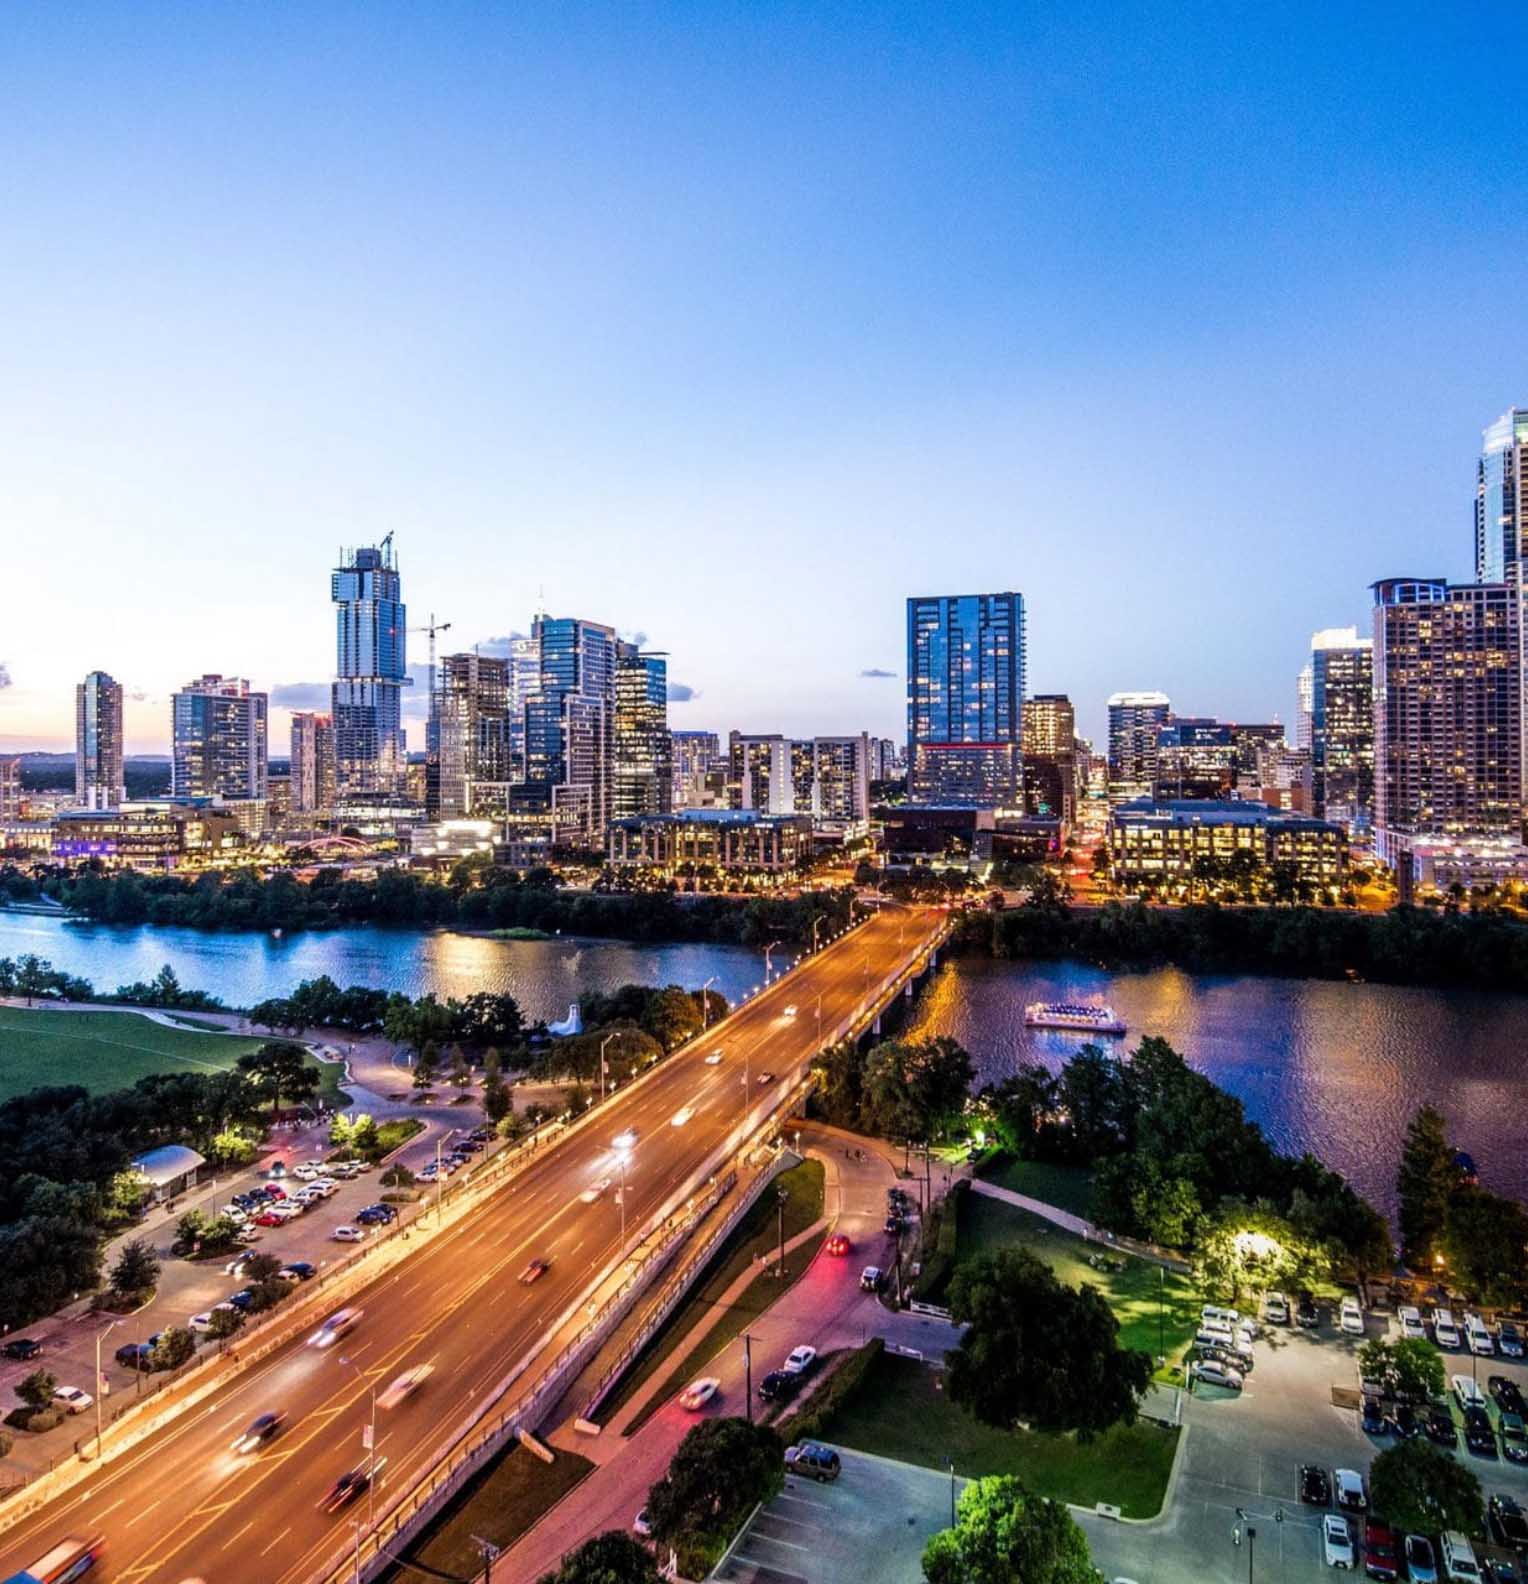
Getting a mortgage in Austin follows the same basic path as anywhere in Texas, but a few local details can shape your budget and the loan you choose. This guide walks through each step, from your first budget to closing day.
Austin Details That Affect Your Mortgage
County lines: Most of Austin is in Travis County, with parts of the city in Williamson and Hays counties. The county, school district and other taxing units for a specific address set its property tax rate.
Taxes and insurance: Property taxes and homeowners insurance are major parts of a Texas mortgage payment, so include both in every estimate.
Loan size: Home prices in parts of the Austin area may push some loan amounts above conforming limits and into jumbo loan territory.
Homestead exemption: Once you own the home and live in it as your primary residence, you may apply for the Texas homestead exemption, which can reduce its taxable value.
Richard Haskell is an experienced Senior Mortgage Loan Officer with a proven track record of excellence in the financial services industry. His expertise includes sales, credit analysis, FHA financing, VA loans, and sales management. Richard is dedicated to delivering exceptional service and expertise to his clients, leveraging his degree from Webster University to provide a solid foundation in finance.
Throughout his career, Richard has consistently achieved outstanding results by understanding his clients' needs and customizing solutions to meet their unique financial goals. His commitment to maintaining the highest standards of professionalism and integrity ensures a seamless and successful loan process for every client.
The most exciting and enjoyable part of a real estate transaction for Reef has always been financing. Today Reef enjoys managing Texas United Mortgage where he works and mentors borrowers, realtors, his team of loan officers, and staff! When not exceeding clients' expectations, Reef enjoys spending time with his wife Valerie and his two daughters. Reef’s hobbies include golf and tennis!
Prior to Reef’s Mortgage/Real Estate career, Reef graduated at Texas A&M University. After graduation, Reef took a teaching/coaching position at The Woodlands High School, located in The Woodlands, Texas.
Scott attended college in his home state of Indiana while playing tennis in college. Wanting to start a new life after school in a new state he moved to Texas 13 years ago. When moving to Houston, he worked as a tennis coach teaching younger children. Alongside working with Reef, Scott also began to invest in real estate and flip houses.
After finishing his career in tennis he moved on to being a loan officer, where he now works at Texas United Mortgage, as a producing loan originator and the operations manager assisting Reef Merhi, Kristy Taylor and Team! He is very passionate about what he does and loves helping people. People know Scott as being a family man. He enjoys spending time with his wife and three children – Case, Cali & Crew. Scott’s hobbies include woodworking, golfing, fishing and playing tennis.
Claudia is a fifth-generation Texan and longtime Woodlands resident since 2004. A dedicated professional in the Texas real estate industry since 2001, she has successfully navigated and closed a wide range of transactions, always ensuring contracts meet every agreement and condition. Claudia is known for her high fiduciary standards, consistently acting with integrity, confidentiality, and the best interests of her clients at the forefront.
Today, Claudia brings her experience and energy to Texas United Mortgage, where she serves as Executive Assistant to Reef and the team. Her goal is to keep the team moving efficiently by ensuring meetings are organized, schedules/files are coordinated, communication flows smoothly, and key administrative tasks bridge gaps in operations.
In addition to her role at Texas United Mortgage, Claudia continues to serve clients as a Texas Realtor, combining her deep industry knowledge with a passion for helping families achieve their homeownership goals.
Outside of work, Claudia treasures time with her husband and two sons. She is an active member of Faith Bible Church, where she enjoys serving her community. When she’s not working or volunteering, you’ll likely find her RVing with her family, enjoying the outdoors, or staying active with regular workouts.
Step 1: Set a Budget Around the Full Monthly Payment
Start with a payment you are comfortable with, not the most you might qualify for. Estimate principal and interest, property taxes for the specific Travis, Williamson or Hays County address, homeowners insurance, any mortgage insurance and HOA dues, and leave room for maintenance and savings.
Step 2: Prepare Your Credit and Savings
Check your credit reports, correct any errors and keep balances low with on-time payments. Build savings for your down payment, closing costs and reserves at the same time. If upfront costs are the obstacle, review down payment assistance in Texas; eligibility depends on the borrower and property.
Step 3: Get Pre-Approved
A loan officer reviews your credit, income, assets and debts and issues a pre-approval letter showing how much you may be able to borrow. Be ready to share a photo ID, pay stubs, W-2s or tax returns, bank statements and information on your debts. A pre-approval strengthens an offer, but it is not a final loan commitment.
Work with a real estate agent who knows the Austin-area neighborhoods you are considering. Share your pre-approval so you tour homes in your range, and ask how each property's county and taxing units affect its tax bill.
Step 5: Lock Your Rate and Complete Underwriting
Once your offer is accepted, you will finalize your application, decide when to lock your rate and order the appraisal. Review your Loan Estimate for the rate, APR, fees and cash to close. During underwriting, avoid new credit, job changes or large unexplained deposits.
Step 6: Close and File for Your Homestead Exemption
You will receive a Closing Disclosure at least three business days before closing to compare with your Loan Estimate. After you sign and move in, file for your homestead exemption with your county appraisal district if the home is your primary residence.
Texas United Mortgage, LLC (NMLS #2442778) is based in The Woodlands and serves borrowers in Austin and the surrounding Travis, Williamson and Hays County areas.
Options for higher loan amounts and self-employed income
Along with conventional, FHA and VA loans, we can help you compare jumbo, bank statement and DSCR options. Program availability depends on your situation and the property.
The right program depends on your credit, income, savings, the property and how you plan to use it. Eligibility depends on the borrower and property.
Conventional and Jumbo Loans
Conventional loans are not government-insured and can be used for primary homes, second homes and investment properties. Credit and down payment requirements vary by program, and mortgage insurance generally applies with less than 20% down.
When a loan amount exceeds the conforming limit, a jumbo loan may be needed. Given home prices in parts of the Austin area, some buyers may fall into this category; compare today's jumbo loan rates in Texas.
Self-employed borrowers may consider a bank statement loan, and investors buying rental property may look at a DSCR loan.
FHA, VA and USDA Loans
FHA loans are government-insured and open to first-time and repeat buyers who meet the guidelines. They offer more flexible credit standards, require mortgage insurance and are capped by county limits (see FHA loan limits in Texas).
VA loans serve eligible veterans, service members and some surviving spouses and may require no down payment. See today's VA loan rates.
USDA loans are for eligible properties in qualifying rural areas; some outlying areas around Austin may qualify.
Why does it matter which county my Austin home is in?
Austin is mostly in Travis County, with parts in Williamson and Hays counties. The county, school district and other taxing units for an address set its property tax rate, which affects your monthly escrow payment.
Will I need a jumbo loan to buy in Austin?
Only if your loan amount is above the conforming limit. That depends on the purchase price and your down payment, and higher prices in parts of the Austin area may push some buyers into jumbo financing.
Do I have to be a first-time buyer to use an FHA loan in Austin?
No. FHA loans are available to first-time and repeat buyers who meet the program guidelines and plan to live in the home, subject to county loan limits.
When should I lock my rate on an Austin purchase?
Most buyers lock after their offer is accepted, choosing a lock period long enough to reach the closing date. Your loan officer can explain lock options and their costs.
Planning an Austin home purchase?
Talk with a licensed Texas loan officer about your budget, county costs and loan options, or request a custom rate quote.
Texas United Mortgage, LLC · NMLS #2442778 · 2170 Buckthorne PL STE 200, The Woodlands, TX 77380 · 888-505-1718